Main Office

303 Convention Way, Suite 4
Redwood City, CA 94063

Branch Office

New Orleans, LA

Financial Checklist for California Horse Boarding Facilities Part 1

What Boarders, Trainers, and Stable Operators Should Know About the Money Behind the Barn

Running a horse boarding facility is much more than feeding horses, cleaning stalls, and maintaining fences. A successful equine operation also requires disciplined financial management, accurate records, properly structured agreements, and compliance with California tax and employment requirements.

For boarders and trainers, understanding the financial side of a boarding operation can help prevent surprises, clarify who is responsible for what, and create a healthier business relationship with the facility.

This checklist is designed for California equine boarding facilities, boarders, and trainers as a practical starting point for financial organization and compliance.

Important: This article is educational information, not legal or tax advice. California employment, tax, and professional-accounting requirements can vary depending on the structure and activities of a particular operation. A boarding facility should consult its California CPA, payroll professional, employment attorney, and/or other appropriate professional before relying on this checklist.

  1. Start With a Written Boarding Agreement

Every boarding relationship should begin with a clear written agreement.

At a minimum, the agreement should identify:

  • Boarder’s name and contact information
  • Horse’s registered or identifying name
  • Type of boarding provided
  • Monthly or periodic boarding fee
  • What services are included
  • What services are billed separately
  • Payment due date
  • Late-payment policy
  • Returned-payment fees, if applicable
  • Training, lesson, or exercise charges
  • Veterinary and farrier authorization procedures
  • Emergency-care procedures
  • Responsibility for veterinary and other third-party expenses
  • Cancellation and termination provisions
  • Requirements for removing the horse from the facility
  • Insurance responsibilities
  • Facility rules and horse-care requirements

Financial best practice: Avoid relying on verbal promises regarding what is included in “board.”

For example, “full board” should be defined. Does it include hay? Grain? Supplements? Blanketing? Holding for the farrier? Medication administration? Turnout? Stall cleaning? What happens when a horse requires additional care?

A written agreement turns assumptions into documented expectations.

  1. Separate Boarding Revenue from Other Services

Boarding facilities frequently provide multiple services under one roof.

Your accounting system should distinguish among revenue categories such as:

  • Stall or pasture board
  • Training
  • Lessons
  • Exercise riding
  • Horse sales or commissions
  • Trailer parking
  • Layovers
  • Blanketing
  • Medication administration
  • Holding for veterinarian or farrier
  • Grooming
  • Clipping
  • Show preparation
  • Hauling
  • Facility rentals
  • Arena rentals
  • Clinics or events
  • Tack or equipment sales
  • Feed or other separately billed items

This is important because different types of charges can receive different accounting and tax treatment.

California’s Department of Tax and Fee Administration specifically addresses transactions involving boarding and training facilities. For example, when a facility charges a flat fee that includes feed, the facility generally is treated as the consumer of that feed; when taxable merchandise such as feed is separately itemized and sold to the customer, the facility may instead be acting as a retailer. (CDTFA)

Bottom line: Don’t assume that everything appearing on a boarding invoice receives the same tax treatment.

  1. Know Exactly What Is Included in the Monthly Board

A financially healthy facility should be able to explain the economics behind its board rate. For example:

Base Board

  • Stall or pasture
  • Hay/feed
  • Water
  • Stall cleaning
  • Basic turnout
  • Arena/facility access

Additional Services

  • Training rides
  • Lessons
  • Blanketing
  • Supplements
  • Medications
  • Special feeding
  • Holding for appointments
  • Grooming
  • Farrier handling
  • Veterinary handling
  • Emergency services

Boarders should receive an invoice or statement that makes it reasonably clear what they are paying for.

Facilities should also periodically review whether their board rate still covers the actual cost of providing services.

  1. Track the Real Cost of Hay and Feed

Feed costs can be one of the largest and most volatile expenses in an equine operation. Facilities should track:

  • Hay purchases
  • Grain and concentrates
  • Supplements
  • Bedding
  • Delivery charges
  • Storage losses
  • Waste
  • Price increases
  • Special dietary requirements

Consider calculating an approximate feed cost per horse per month.

This gives the operator a better basis for determining whether the current board rate remains economically sustainable.

For boarders, significant changes in feed prices may explain why a facility needs to modify its rates—but any increase should be handled according to the written boarding agreement and applicable law.
Treasury, IRS issue guidance on rollovers between retirement plans and individual retirement accounts

WASHINGTON, Aug, 2026 — The Department of the Treasury and the Internal Revenue Service today provided guidance to simplify and standardize the rollover process by issuing sample forms for direct rollovers to or from a retirement plan, as required under the SECURE 2.0 Act section 324.

Notice 2026-49 PDF provides sample forms and proposed rollover procedures and protocols that aim to simplify and standardize the rollover process for both participants and plan sponsors:

  • Scope: It applies to rollovers between retirement plans or between a retirement plan and an individual retirement account (IRA), but not to IRA-to-IRA transfers.
  • Design: The sample forms are designed to protect participants’ personal identifying information and minimize participants’ burden.
  • Optional use: Use of the sample forms and proposed procedures is optional for plan sponsors.

“The IRS continues to look for ways to make complying with tax law less difficult and confusing for taxpayers and to improve tax administration in this complex area of the law,” said IRS Chief Executive Officer Frank J. Bisignano. “The sample forms will make compliance simpler and easier for both plan participants and administrators.”

Equine Industry – Core Services Offered

Monthly Recurring Revenue

  • Bookkeeping packages 
  • Payroll processing 
  • Sales tax filing 
  • Financial reporting 
  • Advisory retainers 

Seasonal Revenue

  • Tax preparation 
  • Tax planning 
  • Entity structuring 
  • Audit support 
  • IRS/state notices 

Premium Advisory Services

  • Business growth consulting 
  • Profitability analysis 
  • Succession planning 
  • Inventory controls for tack/feed stores 
  • Cash flow forecasting 
  • QuickBooks setup and cleanup 

3 Common
Tax Mistakes Farriers Make

A farrier’s mobile workshop creates accounting and tax issues that can easily be overlooked—from specialized equipment and vehicle expenses to California depreciation differences and sales-tax obligations.

Our experienced CPA firm understands the accounting and tax issues affecting the equine industry and professional farriers. We can help you identify lawful tax-planning opportunities, meet your compliance obligations, and make informed financial decisions. Tax treatment and outcomes depend on each client’s individual circumstances.

Here are three common issues professional farriers should consider: 

1. Overlooking the De Minimis Safe Harbor

Eligible businesses may elect to deduct qualifying tools and equipment costing up to $2,500 per invoice or item rather than capitalizing and depreciating them. Specific recordkeeping, accounting-policy, and tax-return requirements apply.

2. Overlooking Federal and Multistate Depreciation Differences

State tax rules do not always follow federal depreciation provisions. California and some other states limit or disallow certain federal deductions, including bonus depreciation, while others conform more closely to federal law. Farriers operating or filing returns in multiple states may need separate depreciation schedules and state-specific adjustments to avoid reporting errors or unexpected tax liabilities.

3. Misclassifying Sales and Service Revenue

Charges for trimming and other services may be treated differently from sales of pads, treatments, or other tangible products. The correct sales-tax treatment—and applicable district tax—depends on what is sold, how it is invoiced, and where the transaction occurs.

Don’t let one-size-fits-all tax preparation overlook the details of your farrier business. Email us at info@llopezcpa.com or call 650-361-1235, extension 3, to discuss whether our firm would be a great fit for you!

Tax Scams Related to the One, Big, Beautiful Bill (Part 1)

The One, Big, Beautiful Bill introduces new and expanded tax benefits. While these changes may help taxpayers, they can also create confusion, especially during the first filing season when they apply. Scammers often exploit uncertainty surrounding new laws.

Taxpayers should watch for the following OBBB-related scams and take steps to protect their personal and financial information.

Ghost preparers exploiting new credits

Unlicensed or unethical tax preparers may promise large refunds by aggressively or falsely claiming new OBBB credits. These preparers may:

  • Exaggerate eligibility for deductions
  • Claim credits that taxpayers do not qualify for
  • Disappear after filing, leaving the taxpayer responsible for penalties, interest, or audits

Red Flag: The preparer refuses to sign the return or provide a valid Preparer Tax Identification Number.

Tips and overtime deduction scams

Dishonest tax preparers advertise “expert” help to claim the tip and overtime deductions, charging excessive fees and inflating amounts on returns. Common tactics include:

  • Promising unusually large refunds tied to tips or overtime
  • Guaranteeing eligibility
  • Inflating or inventing deduction amounts without proper documentation

OBBB provisions require accurate reporting of qualified tips and overtime. Because early information forms may not clearly reflect these amounts, scammers can exploit the complexity to justify improper claims.

Red Flag: The preparer will not explain how amounts were calculated, or claim documentation is unnecessary.

Deduction for seniors “enrollment” scam

The new OBBB deduction for seniors does not require enrollment, advance registration, or third-party sign-up. Eligible seniors can claim the deduction when filing their tax return with the IRS.

Scammers may target seniors through unsolicited calls, texts, emails, or mailers that claim they must:

  • Enroll immediately to receive the deduction
  • Verify personal information to qualify
  • Pay a processing or application fee
  • Click a link and provide their Social Security number or bank information

Red Flag: The preparer claims you must enroll, register, or pay a fee to receive the deduction. The IRS does not require “enrollment” or payment to claim a deduction.

Need To File An Amended Return?

IRS Tax Tip 2026-35, April 28, 2026

Taxpayers who discover an error after filing a federal tax return may need to file an amended return. There are some instances where an amended return isn’t required such as when the IRS corrects errors during processing or requests missing forms or schedules separately.

Reasons to file an amended return

If there are changes to key items on the original return, including:

  • Filing status
  • Income
  • Deductions
  • Credits
  • Dependents
  • Tax liability

Taxpayers can use the Should I file an amended return? tool within the IRS Interactive Tax Assistant to help decide if they should file an amended return to correct an error or make other changes if they already filed.

Time limits

To claim a refund, an amended return must generally be filed within:

  • Three years from the date the original return was filed, or
  • Two years from the date the tax was paid, whichever is later

If the original return was filed early, the three-year period begins from the April tax deadline. Special rules apply when there are net operating losses, foreign tax credits, bad debts or other issues. Additionally, taxpayers in disaster relief situations, combat zone service, have bad debts, foreign tax credits, or loss or credit carrybacks, may have more time to file an amended return.

How to file an amended return

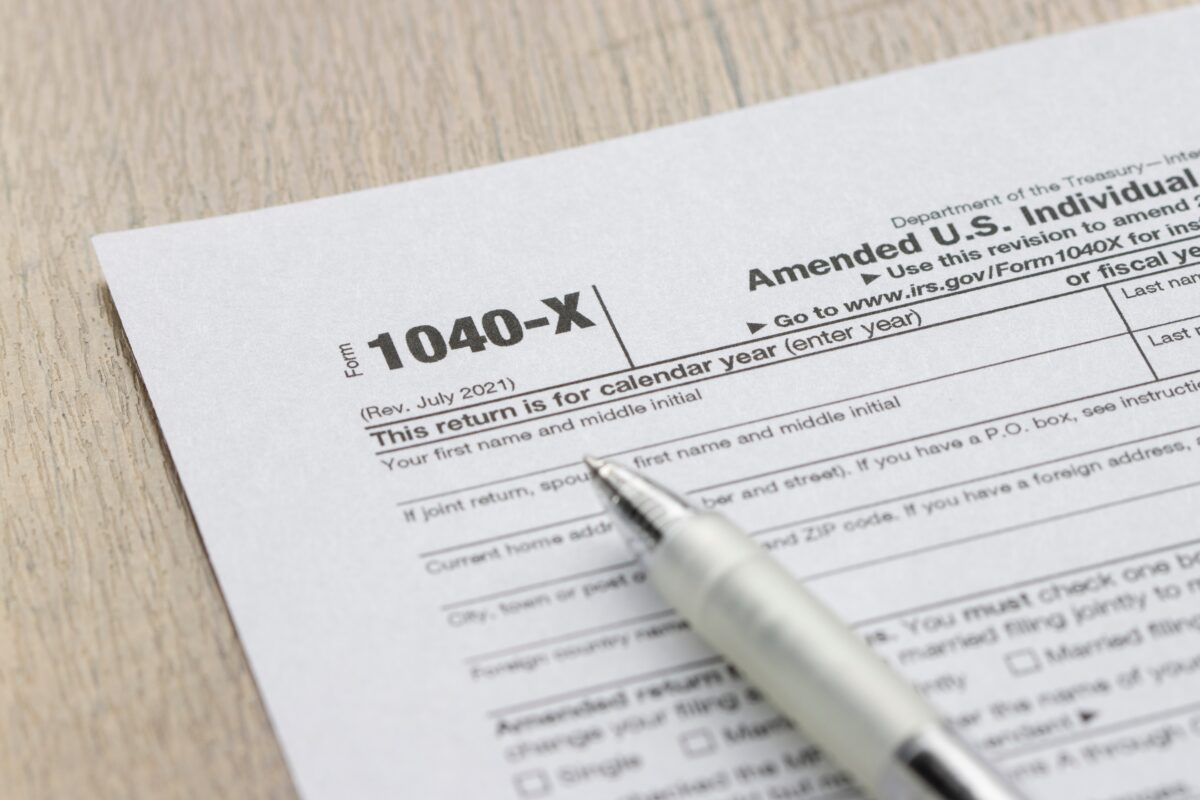
Taxpayers must file Form 1040-X, Amended U.S. Individual Income Tax Return. When filing, they should:

  • Submit a corrected Form 1040, 1040-SR, or 1040-NR for the applicable tax year
  • Attach any supporting documents and updated forms or schedules

Refunds and payments

For tax years 2021 and later, taxpayers may request direct deposit of refunds when filing electronically. If additional tax is owed, payment should be submitted with the amended return. The amended return replaces the original return, and the IRS will calculate any applicable penalties or interest if filed after the due date.

Status of amended return

Taxpayers can check the status of an amended return approximately three weeks after it’s submitted. It generally takes 8 to 12 weeks for it to be processed. However, in some cases, processing could take up to 16 weeks.

State tax considerations

Changes to a federal return may affect a taxpayer’s state tax liability. Taxpayers should contact their state tax agency for guidance and should not attach state returns to the federal amended return.

For More Information Please Visit www.irs.gov

L. Lopez CPA & Associates Offers Services To The Equine Industry

The equine industry is unlike any other business — and your accounting firm should understand that. At L. Lopez CPA & Associates, we combine professional tax and accounting expertise with real-world equestrian experience. From horse trainers and boarding facilities to breeding operations, tack shops, feed stores, equine service providers, and veterinarians, we deliver specialized bookkeeping, payroll, tax preparation, and sales tax services tailored specifically to the horse industry. We understand the financial demands, seasonal cash flow, competition schedules, staffing challenges, and operational complexities unique to equine businesses nationwide

With a background in horse showing, jumper competitions, and equestrian retail operations as owners of the ‘Tie Down Tack Shop for 25 years in Los Altos, California, our team brings industry insight that goes beyond the numbers. We help equine professionals stay compliant, improve profitability, streamline operations, and gain financial clarity so they can focus on running successful programs and caring for their horses and clients.

Whether you manage a large training barn or a growing horse-related business, we provide trusted financial guidance designed to support long-term growth and success in the equestrian world.

Call us today to get started by calling 650-361-1235

Protecting Yourself From IRS Scammers

Know how and when the IRS contacts you so you can protect yourself from impersonators.

Ways The IRS contacts you

The IRS typically contacts you the first time by mail delivered by the U.S. Postal Service.

To verify it’s the IRS, search IRS notices and letters. Some letters are sent from private collection agencies.

Other ways the IRS may contact you:

  • Email – They email only with your permission, with a few exceptions like criminal investigations.
  • Text message – They text you only with your permission.
  • Phone – The IRS or private collection agencies may call you to address account matters. In some cases, IRS uses automated messages that direct you to IRS.gov to securely manage your account, make payments or resolve an issue. The messages don’t share specific details.
  • Fax – They might send a fax to verify or request employment information.
  • In-person visit – These are rare. Find out how and when IRS employees visit you or your business. The IRS generally sends a letter before we visit.

The IRS doesn’t:

  • Direct message or take payment on social media. Follow our social media accounts
  • Accept gift cards or prepaid debit cards as payment
  • Call with automated messages that threaten or direct to websites that aren’t IRS.gov
  • Threaten to call law enforcement or immigration officials
  • Take your citizenship status, driver’s license or business license
  • Mail tax debt resolution advertisements

If the IRS visits you

Unannounced visits are rare. Only 4 types of IRS employees may visit your home or business. Each contacts you in specific ways and carries official identification (ID).

Revenue agents – examinations (audits)

Revenue officers – collections

Special agents – criminal investigations

Fuel inspectors

Identification the IRS carries

Revenue officers, revenue agents and fuel inspectors carry an IRS-issued credential (pocket commission) and HSPD-12 card. Both have the employee’s serial number and photo. You can ask to see both.

  • You may ask to see an additional ID from revenue agents and fuel inspectors.
  • Fuel inspectors also wear uniforms and drive government vehicles.

Criminal Investigation special agents present law enforcement credentials when they investigate.

If you feel unsafe, call 911

If the person doesn’t show you these IDs or you aren’t sure about them, call the number on the card provided by the revenue officer or agent. For more information go to www.IRS.gov

CLIENT 401(k) and IRS UPDATE

401(k) limit increases to $24.5K for 2026…

IRA limit increases to $7,500

WASHINGTON — The Internal Revenue Service announced that the amount individuals can contribute to their 401(k) plans in 2026 has increased to $24,500, up from $23,500 for 2025.

The IRS also issued technical guidance regarding all costofliving adjustments affecting dollar limitations for pension plans and other retirement-related items for tax year 2026 in Notice 2025-67, posted today on IRS.gov.

Highlights of changes for 2026

The annual contribution limit for employees who participate in 401(k), 403(b), governmental 457 plans, and the federal government’s Thrift Savings Plan is increased to $24,500, up from $23,500 for 2025.

The limit on annual contributions to an IRA is increased to $7,500 from $7,000. The IRA catchup contribution limit for individuals aged 50 and over was amended under the SECURE 2.0 Act of 2022 (SECURE 2.0) to include an annual costofliving adjustment is increased to $1,100, up from $1,000 for 2025.

The catch-up contribution limit that generally applies for employees aged 50 and over who participate in most 401(k), 403(b), governmental 457 plans, and the federal government’s Thrift Savings Plan is increased to $8,000, up from $7,500 for 2025. Therefore, participants in most 401(k), 403(b), governmental 457 plans and the federal government’s Thrift Savings Plan who are 50 and older generally can contribute up to $32,500 each year, starting in 2026. Under a change made in SECURE 2.0, a higher catch-up contribution limit applies for employees aged 60, 61, 62 and 63 who participate in these plans. For 2026, this higher catch-up contribution limit remains $11,250 instead of the $8,000 noted above.

The income ranges for determining eligibility to make deductible contributions to traditional Individual Retirement Arrangements (IRAs), to contribute to Roth IRAs and to claim the Saver’s Credit all increased for 2026.

Taxpayers can deduct contributions to a traditional IRA if they meet certain conditions. If during the year either the taxpayer or the taxpayer’s spouse was covered by a retirement plan at work, the deduction may be reduced, or phased out, until it is eliminated, depending on filing status and income. (If neither the taxpayer nor the spouse is covered by a retirement plan at work, the phase-outs of the deduction do not apply.) Check out IRS.gov for more information